Afterpay: Pay over time

Screenshots
Details
- Rating
- 70.66K reviews
- Version
- 1.137.0
- Developer
- Afterpay
Analysis by Norviv
I think the most useful way to judge a pay-over-time shopping app is to ask whether it helps with a planned purchase or simply makes it easier to buy more than you intended. That distinction matters with Afterpay: Pay over time. It is a free shopping app from Afterpay, and its central appeal is spreading a purchase across payments rather than paying the full amount at checkout. I’d treat that as a budgeting tool with real obligations attached, not as extra spending power.
Free to install, but not a substitute for affordability
The app is free to download, which makes trying it out different from paying for a shopping app or subscription. That tells me what access costs: nothing upfront. It does not, by itself, tell me what any particular purchase will cost under every circumstance, so I would check the payment terms shown at checkout before committing. The important value question is not whether the app is free, but whether a payment schedule fits the money I actually expect to have available.
That distinction is easy to overlook when a checkout divides a total into smaller amounts. A lower first payment can feel manageable even when several purchases together would not be. I’d look at the total purchase price first, then consider each scheduled payment alongside rent, bills, and other commitments. If the purchase only seems affordable when I ignore those other obligations, I would wait rather than use a payment option to make the decision feel easier.
Where the convenience earns its place
For a planned item that I need soon, paying in stages can be useful if the schedule is clear and the later payments are already accounted for. The app’s shopping focus also gives it a practical role before checkout: I can browse participating retailers and decide whether the product and price are right before choosing how to pay. That is more helpful than treating the payment method as a reason to shop.
Compared with paying in full by debit card, the appeal is cash flow: the purchase is divided rather than taken from my available balance all at once. Compared with a credit card, it presents a separate payment schedule that I need to track. Neither comparison makes one option automatically better. Paying in full is simpler when I can comfortably afford it, while a credit card may suit someone who already manages its statement and prefers to keep purchases in one familiar account. The right choice depends on the terms, the timing, and my own ability to stay on top of payments.
A practical check before checkout
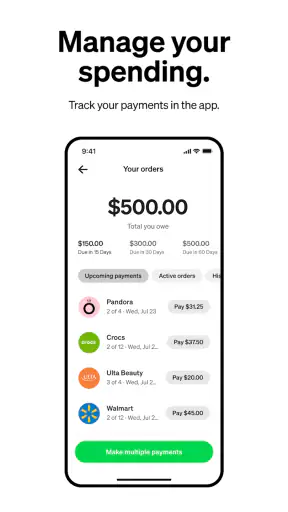
My most useful habit would be to pause before confirming and write down the payment dates and amounts shown for the order. Then I’d compare them with my calendar and expected income, rather than relying on memory. If I’m buying from more than one participating store, I’d repeat that check for each order; several individually small commitments can overlap and become a much larger monthly burden.
I’d also decide in advance what I am buying and set a total limit. Browsing a retailer list can lead to appealing extras, and splitting their cost may make each one seem less significant. Keeping a short shopping list helps separate a genuine need or considered purchase from something I added only because checkout made it feel easier to afford.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Who is likely to get value
This kind of app is most useful for someone with steady control over their spending who wants another way to schedule a purchase and is comfortable keeping track of future deductions. It is less suitable for anyone already juggling missed bills, uncertain income, or several payment plans. In those situations, paying later can add another date to manage without solving the underlying budget problem. Waiting, saving, or choosing a less expensive item may be the calmer option.
Afterpay is rated for Everyone, and its scale is reflected in an average rating of 4.0 from around 169,000 ratings, alongside more than 10 million installs. Those figures suggest a widely used app, but they do not tell me whether its payment approach suits an individual. I would judge that by the checkout terms and my own finances, not by popularity.
What is Afterpay?
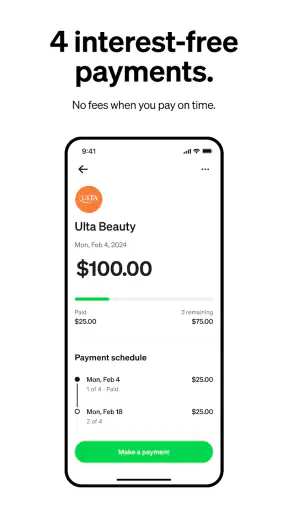
Alright, so let’s get into it. Afterpay is a "buy now, pay later" service that lets you make purchases and pay them off in four equal installments. The best part? No interest if you pay on time! It’s like having a personal finance fairy that helps spread out payments without the stress of interest piling up.
How Does It Work?
Using Afterpay is super straightforward. You just need to download the app from Google Play or the App Store, and set up an account. Once you’re all set, you can shop at your favorite stores that offer Afterpay. At checkout, select the Afterpay option, and voila! You’ve got yourself a payment plan.
Each installment is automatically deducted from your linked debit or credit card every two weeks. The app sends reminders, so you don’t miss a payment. It’s all about making the process as seamless as possible.
User Experience and Features
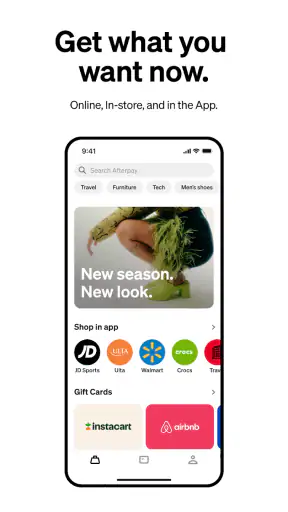
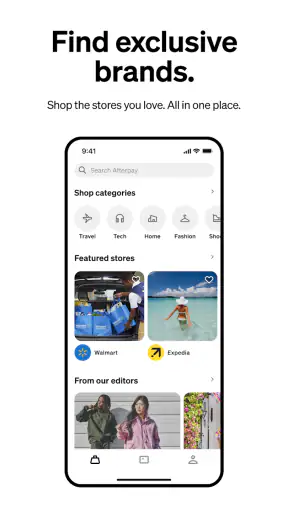
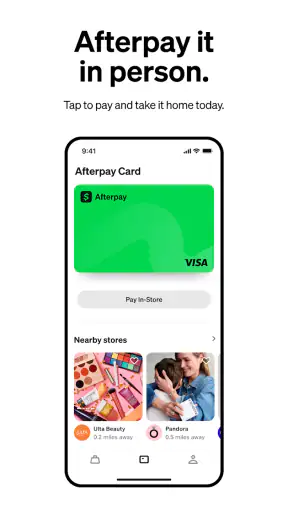
The app itself is pretty sleek. Navigating through it feels intuitive, with a clean interface that lets you find everything you need without any hassle. I love how it showcases a curated list of retailers that support Afterpay, making it easy to discover new stores.
One thing that stands out is the in-app budget tracker. It helps you keep tabs on your spending and upcoming payments. It’s a nifty feature for anyone trying to manage their finances more effectively.
Plus, there’s a rewards program where you can earn points every time you make a payment on time. Collect enough, and you can unlock exclusive offers. It’s like getting a little high-five for being financially responsible.
Security and Trust
I know security is a big deal when it comes to financial apps. Rest assured, Afterpay uses encryption to protect your personal and payment information. They also have a dedicated customer support team in case you run into any issues. It’s always reassuring to know that help is just a message away.
Who Can Benefit?
If you’re someone who likes to shop without putting a dent in your bank account immediately, then Afterpay is definitely worth checking out. It’s perfect for those unexpected splurges or when you want to spread out the cost of a larger purchase.
However, it’s important to use it wisely. While it’s tempting to go on a shopping spree, remember that these are still real payments that need to be made. Keep an eye on your budget and ensure you’re not spending beyond your means.
Choosing it for the right reason
One everyday example makes the trade-off clearer. Imagine I need to replace a pair of shoes before a busy week, and the full cost would make this particular payday tight. If the retailer offers Afterpay and I can comfortably cover every scheduled payment, spreading the cost may help me manage timing without putting the purchase on a credit card. But if I’m choosing a more expensive pair only because the first payment looks small, the app is working against my budget rather than helping it.
I would use the same test for household essentials or a planned seasonal purchase: decide on the item and maximum total first, then see whether the payment schedule fits. I would not use the app to cover recurring costs that I cannot meet, or to make an impulse purchase feel harmless. A payment plan shifts when money leaves my account; it does not make the item cheaper or increase my income.
Questions worth settling before using it
Does free access mean every purchase is free of extra cost? No: free refers to downloading and using the app, while the terms attached to a transaction are what matter for that order. I would read the checkout details rather than assume that every purchase has identical conditions. Can I use it at any store? The practical starting point is the retailer selection in the app and whether Afterpay is offered at that retailer’s checkout; it is not a universal payment method.
What if I am not sure I can meet a later payment? I would not place the order yet. A reminder can help me remember a date, but it cannot make the funds available, and an automatic deduction still needs to fit my account balance. If a purchase is urgent, I’d compare the payment option with paying in full, postponing the purchase, or choosing a lower-cost alternative rather than treating instalments as guaranteed breathing room.
Does the app replace a full budgeting system? I wouldn’t rely on it for that. A tracker for Afterpay spending can help me see commitments made through the service, but I’d still need to account for rent, utilities, other cards, and ordinary spending elsewhere. I’d use it as one view of my shopping payments, not as a complete picture of my finances.
Platform details and everyday fit
The app was released on August 5, 2018, and its current version is 1.137.0. It supports Android 7.0 and later, which is useful to check if I’m installing it on an older device. Afterpay is the developer, and the app belongs to the shopping category; those details tell me where it fits, but the deciding factor remains whether I can manage the payment commitments responsibly.
Its strongest case is convenience for a deliberate purchase from a participating retailer, especially when the schedule suits my cash flow and I have already checked the full amount. Its weakest case is impulse shopping or using one plan to bridge a budget that is already stretched. I’d also prefer the familiar simplicity of paying in full when I have the money available, since that avoids carrying another set of dates in my head.
Final Thoughts
All in all, Afterpay: Pay over time is a handy tool for anyone looking to manage their finances more flexibly. It’s easy to use, secure, and comes with features that make shopping a little more fun and a lot less stressful. Just remember to shop smart, and you’ll be golden.
If you’re curious to try it out for yourself, you can download it from the links below and start exploring a new way to pay. Happy shopping!
Frequently Asked Questions
01What is Afterpay and how does it work?
Afterpay is a financial service app that allows you to purchase items immediately and pay for them later in four equal installments. Once you set up an account, you can shop with participating retailers, and afterpay will automatically split the cost. This way, you can enjoy your purchases without paying the full amount upfront.
02Is there an interest or fee when using Afterpay?
Afterpay does not charge any interest on your purchases. However, if you miss a scheduled payment, a late fee may apply. It’s important to keep track of your installment due dates to avoid any additional charges. The app sends reminders to help you stay on top of your payments.
03What are the eligibility requirements for using Afterpay?
To use Afterpay, you must be at least 18 years old, have a valid and verifiable email address and phone number, and have a credit or debit card to link to your account. Afterpay also requires that you reside in a country where the service is available, such as the United States, Australia, or the UK.
04How does Afterpay affect my credit score?
Afterpay does not perform a credit check when you sign up or use the service, so it doesn’t affect your credit score. However, consistently missing payments could lead to account restrictions. Practicing responsible payment habits is crucial to maintain a good standing with Afterpay and avoid any impact on your credit reputation.
05Can I use Afterpay in-store and online?
Yes, Afterpay can be used both in-store and online with participating retailers. To use Afterpay in-store, check the app for a barcode or code to present at checkout. For online purchases, simply select Afterpay as your payment option during the checkout process. Be sure to check the app for a list of supported stores.


